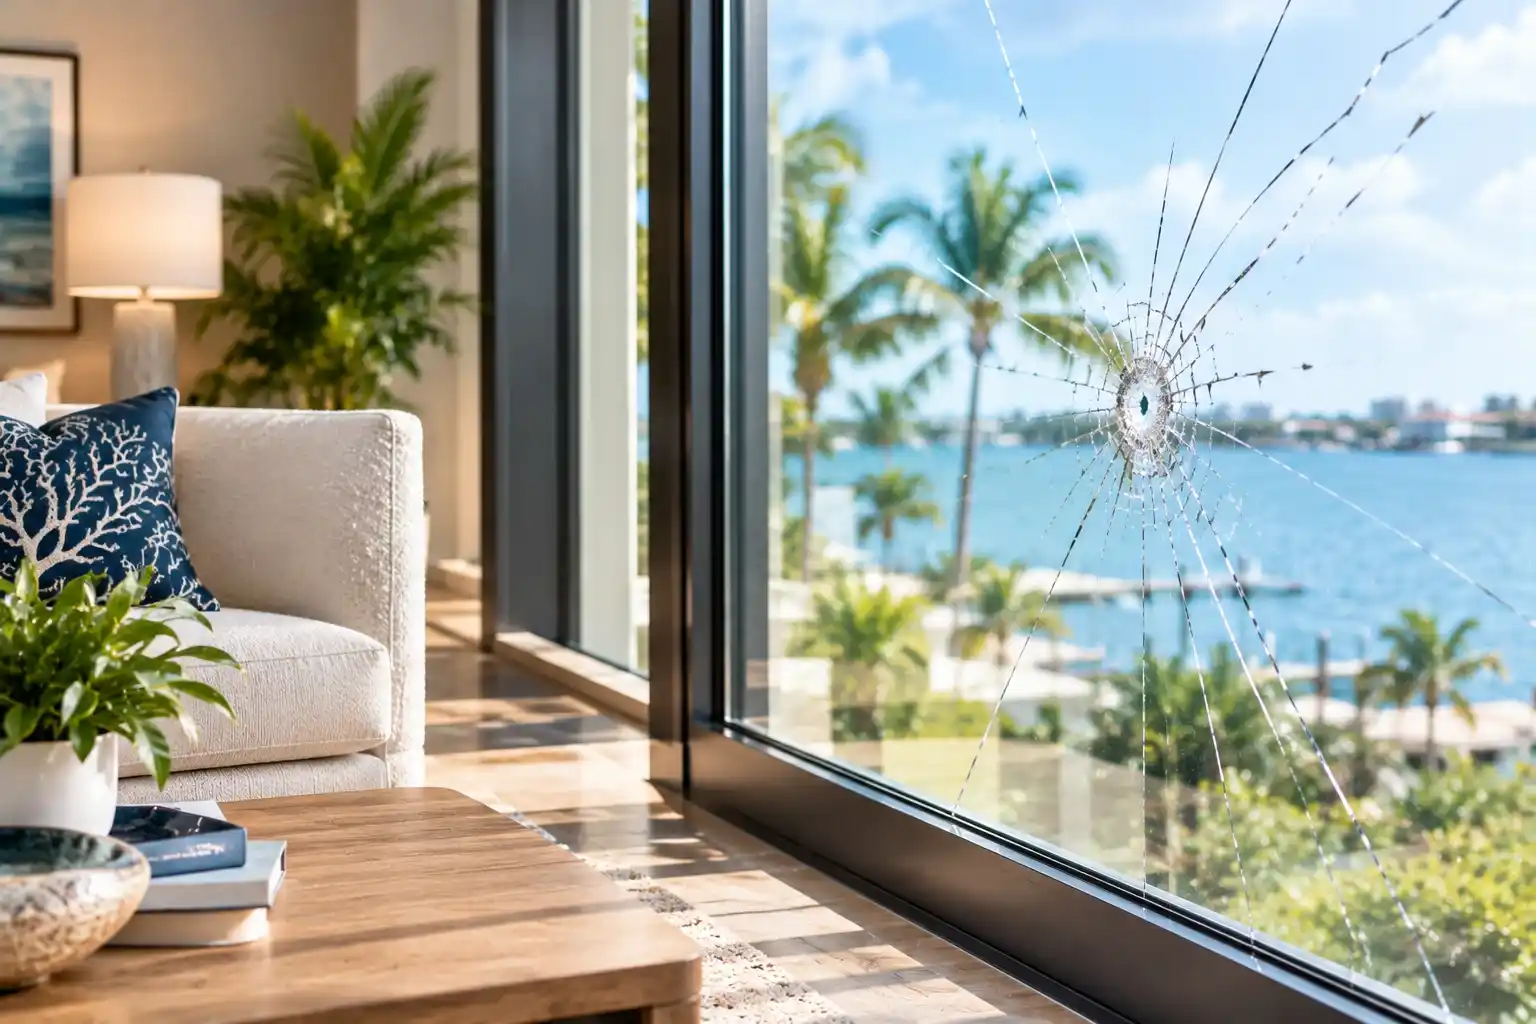
Does Insurance Cover Glass Repair Damage in Florida Homes?
A cracked window after a storm raises an obvious question before any repair call gets made. Does insurance cover glass repair damage, or is this an out-of-pocket expense? The honest answer depends heavily on what caused the damage and what a specific policy actually says, which is why so many Florida homeowners end up confused after their first claim. A little clarity before that first phone call to an insurer can save weeks of back and forth later.
Florida law requires most residential property policies to include windstorm coverage, but that requirement comes with conditions, exclusions, and a separate deductible structure that catches many homeowners off guard. Understanding these basics before filing a claim can prevent unnecessary delays and confusion. Working with a Luxurious Glass can properly document the damage and also gives homeowners stronger records to provide their insurer. Even a technically covered loss can get delayed or disputed when the supporting evidence is thin.
Not every broken or foggy pane qualifies as storm damage in the eyes of an insurer, and that distinction matters enormously. A shattered window from wind-driven debris during a named storm looks very different on a claim form than a slowly failing seal that has nothing to do with weather at all, even though both might get discovered on the very same day.
This guide covers whether insurance covers glass repair damage in most Florida policies, what qualifies as a legitimate storm-related claim, and how the process differs depending on the actual cause of the damage.
Does Insurance Cover Glass Repair Damage in Florida?
Whether insurance covers glass repair damage comes down almost entirely to cause. Florida Statute 627.712 generally requires residential property insurers to include windstorm coverage, meaning wind-related glass breakage during a declared storm is typically covered under most policies, subject to the applicable deductible. This requirement exists specifically because Florida's hurricane exposure is high enough that lawmakers decided homeowners should not be left without any wind protection at all.
Damage from anything other than a covered peril tells a different story. Full glass repair and replacement services often see this confusion firsthand, since a homeowner assumes any broken glass qualifies for a claim when gradual wear, poor installation, or simple accidents frequently fall outside standard coverage entirely.
For damage that requires a new pane or a made-to-measure replacement, custom glass may be part of the repair process, depending on the opening and specifications. An insurer evaluating a claim will typically ask pointed questions about exactly how and when the glass broke before agreeing to pay anything.
Glass Repair Storm Damage Insurance: What Typically Qualifies
Glass repair storm damage insurance generally applies when wind, wind-driven debris, or a named storm causes the actual breakage. The key factor is whether the storm directly caused the damage.
Wind-Driven Damage: A window shattered by a tree branch during a tropical storm may qualify as storm-related damage. A door cracked by flying debris during a hurricane may also qualify.
Storm Severity: Even a relatively minor storm can cause qualifying glass damage. The size of the weather event matters less than whether wind directly caused the breakage.
Documented Connection: Insurers typically look for clear evidence connecting the storm event to the damage. Photos, timing, and visible debris can help establish that connection.
Impact-Rated Glass: Impact-rated glass can provide both protection and useful product documentation. Florida’s hurricane zone glass safety standards explain the requirements surrounding impact-rated glass and its role in Florida properties.
A storm inspection can also highlight other glass features that may need attention or updating. For homeowners planning interior improvements alongside necessary repairs, residential custom mirrors can be incorporated into the property's overall glass upgrade plans.
Filing a Homeowners Insurance Glass Claim: What to Document
A homeowners insurance glass claim moves faster and more smoothly when documentation happens immediately. Photos of the damage from multiple angles, the date and time of the storm event, and any visible debris near the broken glass all strengthen a claim before an adjuster ever arrives. Waiting even a few days to document the scene, especially if cleanup happens quickly, can leave a homeowner with less evidence than they realize they will need.
Water intrusion following broken glass deserves particular attention, since secondary damage often costs more to repair than the glass itself. Pre-existing issues with sliding glass systems can also complicate a claim if an insurer argues that the damage predates the storm. Proper documentation helps establish whether the water intrusion resulted from the storm or existed beforehand.
Your Claim Is Only as Strong as Your Documentation.
Insurers do not pay for what they cannot verify. Photos, timing, and clear evidence connecting damage to a storm decide most glass claims. Luxurious Glass documents damage properly for Southwest Florida homeowners before a claim is filed.
Hurricane Glass Damage Claim: Deductibles and Timing
A hurricane glass damage claim in Florida operates under a different deductible than routine homeowners claims.
State law sets hurricane deductibles as a percentage of the dwelling coverage limit, commonly 2, 5, or 10 percent, rather than a flat dollar amount, which can mean thousands of dollars in out-of-pocket cost before coverage kicks in. Many homeowners are surprised to learn this figure only when they finally read their declarations page closely for the first time.
Timing also matters more than many homeowners expect. Filing a hurricane glass damage claim promptly after a storm, rather than weeks later, reduces the chance an insurer questions whether the damage actually occurred during the covered event.
Reviewing interior hurricane safety tips for glass and mirrors before storm season begins can also reduce the odds of damage in the first place, which is always preferable to navigating a claim after the fact.
How Florida Insurance Typically Treats Glass Damage
The table below summarizes how glass damage is generally treated under Florida homeowners policies, based on current state insurance law.
Source: Florida Statutes, Chapter 627, Section 627.712, residential windstorm coverage requirements
A glass repair insurance claim in Southwest Florida frequently gets complicated by exactly this distinction, since coastal homes see both storm-related breakage and ordinary seal failure at similar rates.
Homeowners preparing for the season, including those away for part of the year, often benefit from reviewing their snowbird home maintenance plans and checking for developing issues before they become disputed claims. Damage discovered after returning home can be harder to date accurately than damage documented immediately.
When Glass Damage Is Not Covered
Not every glass problem becomes an insurance claim. Gradual deterioration is treated differently from sudden damage caused by a covered event.
Foggy Insulated Glass: A slowly fogging insulated glass unit usually does not qualify for coverage because seal failure is considered gradual deterioration.
The Timing Can Be Misleading: Fogging that becomes noticeable after a storm does not necessarily mean the storm caused it. The underlying seal may have been weakening for months or years.
Routine Maintenance: When the seal has failed gradually, the issue is generally treated as maintenance rather than a sudden, accidental loss.
The distinction matters when deciding whether to file a claim. When a failed seal causes the problem, insulated glass replacement for foggy windows may be the appropriate solution rather than filing an insurance claim.
Protecting Glass Before the Next Storm Reduces Claim Headaches
Preventive steps taken before storm season reduce both the likelihood of damage and the complexity of any claim that does eventually get filed. Impact-rated glass, properly maintained seals, and documented pre-storm condition all strengthen a homeowner's position if damage does occur, since a clear before-and-after record removes much of the ambiguity insurers otherwise rely on when questioning a claim.
Damage from anything other than a covered peril tells a different story. Homeowners may still need glass repairs and replacements when gradual wear, poor installation, or accidents cause the damage. These situations, however, may fall outside standard insurance coverage.
Know Before You File
Does insurance cover glass repair damage in Florida? Often, yes, when the cause is clearly tied to wind or a covered storm event, but far less reliably when the damage stems from gradual wear or an unrelated accident. Glass repair storm damage insurance depends heavily on documentation, and a well-prepared homeowners insurance glass claim moves through the process far more smoothly than one filed without supporting evidence.
Licensed glass repair and replacement services throughout Southwest Florida can help document damage properly for insurance purposes. Get in touch with us today for an assessment before filing your claim.
Start Your Project Today
Frequently Asked Questions
Does insurance cover glass repair damage caused by a hurricane?
Generally yes, since Florida law requires most residential policies to include windstorm coverage, though a separate hurricane deductible typically applies.
Is glass repair damage covered by homeowners insurance in Florida for non-storm accidents?
Sometimes, depending on the policy's other perils coverage, though many policies distinguish between sudden accidental damage and gradual wear when deciding what qualifies.
What does glass repair storm damage insurance typically require for approval?
Clear documentation connecting the damage to a specific storm event, including photos, the date of the storm, and evidence the damage was sudden rather than gradual.
How is a hurricane glass damage claim different from a standard claim?
It usually falls under a separate, percentage-based hurricane deductible rather than the policy's standard flat deductible, which can significantly change out-of-pocket costs.
Will a homeowners insurance glass claim cover a slowly fogging window?
Typically not, since gradual seal failure is generally classified as maintenance-related wear rather than a sudden, accidental loss covered under most policies.
Does insurance cover water damage if a storm breaks my window?
If a covered storm shatters your glass and allows rain inside, standard policies typically cover the resulting water damage. Be sure to document the broken window and any interior water intrusion immediately.